Author: EXIT DESK

  • AI Life Insurance Quote Checker for NJ Households 2026

    If the words “life insurance” make your eyes glaze over, you’re not alone. Most people in New Jersey deal with it the same way they deal with DMV mail. Ignore it until it becomes a problem.

    Here’s the thing though. Life insurance in NJ is one of those quiet money leaks. Not flashy. Just bleeding you slowly every month while you’re busy worrying about property taxes, groceries, and why Parkway traffic is somehow worse than last year.

    I found out the hard way that most people are either overinsured or paying way too much for what they have. Sometimes both.

    This is where AI actually earns its keep.

    These new AI quote checkers let you plug in your real situation. Age. Health basics. Family size. Mortgage. Kids. Zip code. All of it. Not the fake “average American” nonsense. Actual New Jersey reality.

    In seconds, it pulls quotes across carriers and shows you the spread. Same coverage. Wildly different prices. Some companies straight up punish NJ residents. Others don’t. You’d never know unless you lined them up side by side.

    What shocked me was how fast it spots junk policies. High premiums. Low payout. Clauses buried so deep you’d need a law degree and a magnifying glass. The tool flags that stuff instantly.

    I’m talking minutes, not days.

    It also shows you when term life actually makes more sense than whole life. Nobody at a kitchen table sales pitch is going to tell you that. Their commission depends on you not knowing.

    If you’ve got a family, a mortgage, or even just someone who’d be screwed if your income disappeared, this isn’t optional adulting. This is protecting your house from becoming a financial disaster overnight.

    And no. This isn’t about buying more insurance. It’s about paying less for the right amount and not getting played.

    End of the day takeaway. If you haven’t checked your life insurance in years, you’re probably overpaying. This is the fastest way to confirm it without talking to a human who’s trying to sell you something.

    Read the full statewide guide:
    https://exitdesk.wordpress.com/2025/12/11/how-new-jersey-residents-are-using-ai-in-2026-to-beat-high-taxes-insurance-rates-and-everyday-costs/

  • Why Britain Really Lost the Revolutionary War: They Wash Dishes Like It’s a Filthy Mop Bucket (And Skip the Rinse!)

    Why Britain Really Lost the Revolutionary War: They Wash Dishes Like It’s a Filthy Mop Bucket (And Skip the Rinse!)

    By Exit Desk | Opinion

    Listen up. I’ve fallen headfirst into one of the most unhinged transatlantic culture debates of all time, and it explains way more about history than it should.

    In Britain, a shocking number of people wash dishes by filling a plastic bowl with hot, soapy water, dumping everything into it, scrubbing away, and then placing the dishes directly on a rack to air-dry. No rinse. No running water. No final cleanup.

    Glasses first. Then plates. Then greasy pans. Then sauce-covered chaos. All in the same murky soup.

    And when they’re done? They just let the soap and leftover grime “dry off.”

    That’s it.

    No rinse.

    That’s like shampooing your hair and skipping the rinse. Like waxing your car and letting the streaks bake in the sun. Like mopping your floor and proudly leaving the dirty water behind because “it’ll evaporate.”

    They insist it’s fine. They defend it aggressively.

    “Order matters,” they say.

    “Scrape the food first.”

    “We use super-concentrated soap.”

    And sure. At the start, the water looks clean. Bubbly. Innocent. Promising.

    Three minutes later, it looks like a crime scene.

    Floating crumbs. Grease slicks. Gray water that resembles a mop bucket more than a sink. And somehow, the next plate still goes in.

    Then straight to the drying rack. Soap bubbles clinging on for dear life. Residue intact. Forks marinating in yesterday’s curry and this morning’s bacon grease.

    Now compare that to the American way.

    We run the tap. We rinse every single dish under fresh water. The grime goes down the drain where it belongs. No recycling dirt. No soap film. No mystery flavor left on your coffee mug.

    Clean dish. Clean water. End of story.

    This isn’t just about dishes. It’s about mindset.

    Britain’s no-rinse method is built on efficiency and tradition. “This is how we’ve always done it.” Minimal water. Minimal change. Maximum confidence that “good enough” is good enough.

    Sound familiar?

    Back in 1776, British troops marched in rigid lines, clinging to outdated tactics, convinced their disciplined efficiency would win the day. Americans didn’t fight that way. We adapted. We improvised. We refused half-measures.

    Same principle. Different battlefield.

    If you’re going to clean something, finish the job. If you’re going to fight a war, adapt. If you’re going to pretend soap residue magically disappears, don’t be shocked when things don’t turn out great.

    So yes. This is why Britain lost the Revolutionary War.

    Not because of taxes. Not because of tea. Because somewhere deep in the national psyche is a comfort with dunking clean things back into dirty water and calling it progress.

    America didn’t settle for that in 1776.

    And we’re still rinsing like champions today.

    Land of the free.

    Home of the thoroughly rinsed dish. 🦅🍽️

  • 33.99% Credit Card APR: Legalized Predatory Extraction That Must End Now

    33.99% Credit Card APR: Legalized Predatory Extraction That Must End Now

    By Exit Desk | Opinion

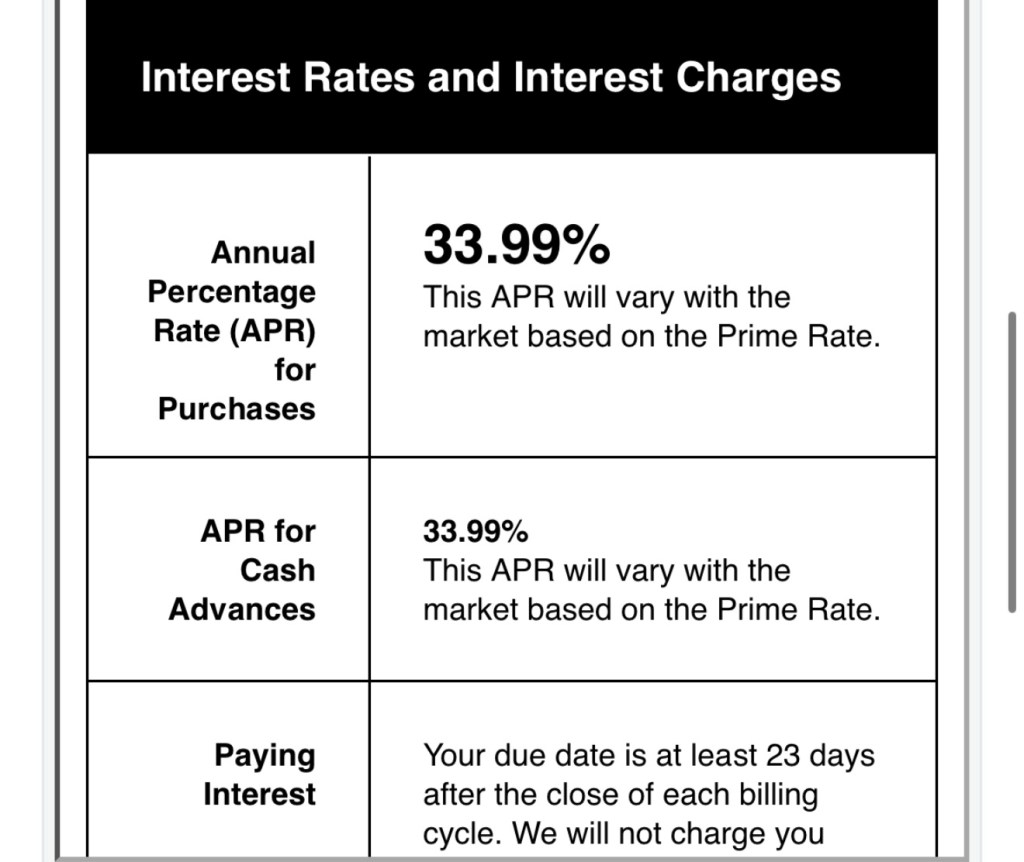
    A 33.99% APR on a credit card is not risk-based pricing. It is not a legitimate market rate. It is deliberate, calculated exploitation.

    As of December 2025, the average interest rate on new credit card offers sits around 22–23%. The prime rate is roughly 6.75%. Yet major credit card issuers continue charging consumers interest rates pushing 34%, 36%, and even higher.

    These are not fringe products. First Premier Bank advertises rates up to 36%. Retail cards, including luxury brands, routinely hit 35.99%. These rates are commonly imposed on Americans with imperfect credit, recent financial hardship, or anyone forced to rely on a cash advance.

    This is not credit. It is a system engineered to extract wealth from people who can least afford it.

    The Brutal Reality of the Math

    At 33.99% APR, compounded daily:

    A $1,000 carried balance costs nearly $340 per year in interest A $5,000 balance burns more than $1,700 annually Minimum payments barely touch the principal, sending most payments straight into interest

    This structure does not promote repayment. It manufactures long-term dependency, turning a temporary emergency into years or even decades of financial stagnation.

    Issuers Know Exactly What They’re Doing

    Banks justify these rates by citing “risk,” yet those same institutions borrow money at a fraction of the prime rate. The difference is not risk management. It is unchecked leverage.

    One missed payment. One medical bill. One emergency repair. The trap closes fast. Even when spending stops, balances continue to grow through interest alone.

    Meanwhile, these cards are aggressively marketed with rewards, cash back, and pre-approval offers. The danger is buried in fine print that most people never read until the damage is already done.

    The Timing Makes This Worse

    Families are already under pressure from inflation, housing costs, insurance premiums, and healthcare expenses. For many households, credit cards are not used for luxury. They are used to survive.

    Adding a near-34% interest rate on top of that is not consumer protection. It is punishment. It deepens inequality, destabilizes families, and locks people into cycles of debt that become increasingly difficult to escape.

    We Once Called This Usury

    For much of American history, excessive interest was recognized as socially destructive. Usury laws existed specifically to prevent this kind of financial harm.

    That changed after the 1978 Supreme Court decision in Marquette National Bank v. First of Omaha, which allowed national banks to export permissive interest rates nationwide from states like Delaware and South Dakota. As a result, local consumer protection laws became effectively meaningless for most credit cards.

    A private lender charging 34% interest would be labeled predatory. When a national bank does it, the practice is normalized.

    This is not an economic necessity. It is a policy failure driven by deregulation and corporate influence.

    A Practical Solution Already Exists

    This problem does not require dismantling the financial system. A federal cap on consumer credit card APRs, tied to a reasonable margin above the prime rate, would immediately reduce harm while still allowing banks to price risk responsibly.

    Many developed countries already enforce similar protections. Their financial systems function just fine. Consumers avoid permanent debt traps.

    The United States has simply chosen not to act.

    The Bottom Line

    A 33.99% APR is not a free-market outcome. It is the direct result of eroded safeguards and regulatory capture.

    If policymakers are serious about protecting consumers, the line should be clear. No credit card should ever be allowed to charge interest at a level that mathematically guarantees entrapment for anyone who stumbles.

    At that point, it stops being credit.

    It becomes extraction.

  • AI Pet Insurance & Vet Cost Tools for New Jersey Families 2026

    Full Article

    Listen. If you’ve got a dog, a cat, or anything with four legs in New Jersey, you already know the deal. You don’t even flinch at vet bills anymore. You just sigh, swipe the card, and hope your bank app doesn’t send you a push notification in public.

    Routine visit. Two shots. Maybe an X-ray. Boom. You’re out $700. For a cat that looks completely fine.

    Here’s the part nobody tells you. Most of that pain is avoidable now.

    New AI tools are quietly changing how NJ families deal with pet insurance and vet costs, and yeah, I was skeptical too. This sounded like another app that promises the world and saves you twelve bucks. It’s not that.

    These tools let you plug in your pet’s age, breed, and where you live. Not generic. Jersey-specific. Shore towns, inland towns, high-cost areas. All of it. Then it compares pet insurance plans that actually work here. Not the ones that deny everything once your dog sneezes.

    Even better. Some of them estimate vet costs before you even walk in. Bloodwork. Dental cleanings. Emergency visits. You can see what’s normal and what’s straight nonsense before you’re standing at the counter feeling trapped.

    I’m talking minutes, not days.

    The real win though is how it flags bad policies. You know the ones. Cheap monthly premium. Looks great. Then you read the fine print and realize they don’t cover half the stuff that actually happens. These tools spot that immediately.

    For NJ families dealing with already insane property taxes, grocery bills, and Parkway tolls, this matters. Pets aren’t optional. They’re family. But that doesn’t mean you should get wrecked financially every time something comes up.

    If you’ve ever left a vet office angry, confused, or wondering if you just got played, this is worth five minutes of your time.

    Punchline. You don’t need to guess anymore. You can walk in prepared. That alone changes everything.

    Pillar Link at the Bottom

    Read the full statewide guide:
    https://exitdesk.wordpress.com/2025/12/11/how-new-jersey-residents-are-using-ai-in-2026-to-beat-high-taxes-insurance-rates-and-everyday-costs/

  • AI Tenant Screening Tools for New Jersey Landlords 2026 (Background + Credit)

    New Jersey landlords face strict screening rules, rising risk, and higher turnover. In 2026, AI-driven tenant screening tools are helping property owners make faster, more accurate decisions without violating state or federal fair housing laws.

    Here’s how AI improves tenant screening across NJ.

    AI reads and interprets background checks

    Landlords often receive long, confusing reports. AI condenses them into:

    • clean summaries
    • timeline of prior addresses
    • conviction breakdowns
    • risk flags
    • recommended follow-up questions

    This prevents misunderstandings that lead to bad approvals.

    AI analyzes income stability

    Instead of a simple “3× rent” rule, AI can review:

    • pay stubs
    • deposit patterns
    • employment history
    • self-employment income
    • payment reliability indicators

    This makes screening more fair and more accurate.

    AI evaluates rental history

    For NJ applicants, rental history is often the strongest predictor of performance. AI reviews:

    • late payments
    • eviction filings
    • property disputes
    • prior lease length
    • landlord notes

    It combines all inputs into a clear risk profile.

    AI helps NJ landlords stay compliant

    New Jersey has rules on:

    • credit usage
    • criminal record consideration
    • source-of-income protection
    • anti-discrimination requirements

    AI reminds landlords which questions they can and cannot ask.

    Tools NJ landlords use

    • TurboTenant AI
    • Zillow Rental Manager AI
    • Avail screening tools
    • RentSpree + AI summaries
    • ChatGPT NJ landlord-tenant law prompts

    Bottom Line

    AI helps NJ landlords screen tenants fairly, accurately, and faster — reducing the risk of costly turnovers and disputes.

    Full statewide guide

    Read the statewide guide:
    https://exitdesk.wordpress.com/2025/12/09/ai-in-new-jersey-the-complete-2026-guide-for-residents-homeowners-teachers-small-businesses/

  • Get Instant Mortgage Pre-Approval Using AI in New Jersey 2026

    AI is transforming mortgage pre-approvals across New Jersey. What once took days now takes minutes, and buyers get more accurate numbers thanks to real-time tax and insurance calculations.

    AI verifies your documents instantly

    Upload:

    • W-2s
    • pay stubs
    • 1099s
    • bank statements
    • employer info

    AI checks for errors, inconsistencies, and missing items before the lender even reviews them.

    AI predicts your true NJ borrowing power

    Unlike old calculators, AI includes:

    • NJ property taxes
    • homeowners insurance
    • flood insurance (where applicable)
    • HOA fees
    • PMI
    • county-level housing trends

    This prevents buyers from falling in love with homes outside their range.

    AI compares loan types

    AI evaluates:

    • FHA
    • VA
    • USDA
    • conventional
    • jumbo
    • NJHMFA programs

    Then it tells you which one will cost less long-term.

    AI speeds up underwriting

    AI organizes documents so lenders can approve faster, reducing surprises later in the process.

    Tools NJ buyers use

    • Better.com AI
    • Rocket Mortgage AI
    • Zillow Mortgage Tools
    • ChatGPT document organizer prompts

    Bottom Line

    AI helps New Jersey buyers secure accurate, fast pre-approvals — a major advantage in competitive markets.

    Full statewide guide

    Read the full statewide guide:
    https://exitdesk.wordpress.com/2025/12/09/ai-in-new-jersey-the-complete-2026-guide-for-residents-homeowners-teachers-small-businesses/

  • Best AI Comps Tools for New Jersey Realtors & Home Sellers 2026

    Finding accurate comps in New Jersey is notoriously difficult. School zones, flood zones, township boundaries, and tax variations can make two nearby homes worth completely different amounts. AI tools in 2026 help realtors and homeowners build more accurate comp sets with less guesswork.

    AI filters out bad comps

    It automatically removes:

    • distressed sales
    • homes outside the true school boundary
    • properties in different flood zones
    • outdated or irrelevant sales
    • mis-matched bed/bath counts

    This creates a more realistic comp set.

    AI reads entire MLS sheets

    AI catches key details that basic estimates miss:

    • finished basements
    • renovations and additions
    • HVAC updates
    • roof age
    • HOA restrictions
    • waterfront premiums

    This mirrors how appraisers analyze value.

    AI makes value adjustments

    Instead of one-size-fits-all rules, AI adjusts based on local NJ markets:

    • square footage
    • garage space
    • lot size
    • upgrades
    • condition
    • proximity to transit

    This produces a comp report more aligned with NJ appraisal logic.

    Tools NJ agents use

    • RPR + AI overlays
    • DataTree AI
    • MLS exports + ChatGPT analysis
    • Redfin advanced data
    • Zillow raw comp feeds

    Bottom Line

    AI gives New Jersey agents and sellers more precise pricing, fewer surprises, and better listing strategies.

    Full statewide guide

    Read the full statewide guide:
    https://exitdesk.wordpress.com/2025/12/09/ai-in-new-jersey-the-complete-2026-guide-for-residents-homeowners-teachers-small-businesses/


  • Verified New Jersey Guides for Taxes, Insurance, Benefits and Costs

    Update: This broad page previously claimed free AI tools could slash taxes, find cheaper insurance, uncover grants and produce large savings. Those claims were not adequately supported and duplicated Exit Desk’s current verified-guide navigation.

    Browse Verified New Jersey Consumer Guides: Taxes, Insurance, Benefits and Costs

    The hub routes readers to current, source-backed guides for distinct decisions instead of promising one AI workflow can solve unrelated legal, tax, insurance and benefit questions.

    This URL is retained so existing links reach the corrected navigation resource.

  • New Jersey Contractor Insurance Requirements: General Liability and Workers’ Comp

    New Jersey home-improvement contractor businesses generally must document at least $500,000 per occurrence in commercial general liability coverage and maintain workers’ compensation insurance when required by law. Public-work contracts, home-elevation work, vehicles, professional services, and particular clients can require additional coverage or much higher limits.

    This guide explains the baseline rules and how contractors should compare policies. It does not promise the “cheapest” insurer or quote a statewide average because premiums depend on trade, payroll, revenue, subcontracting, limits, claims, location, and operations.

    Home-improvement contractor registration

    The New Jersey Division of Consumer Affairs requires a home-improvement contractor business to file proof of commercial general liability insurance with a minimum limit of $500,000 per occurrence. The registration FAQ also requires workers’ compensation insurance unless the business is exempt by law.

    The $500,000 figure is a registration minimum, not a recommendation that it is adequate for every job. A customer, general contractor, landlord, lender, municipality, or commercial contract can require higher limits and specific endorsements.

    Workers’ compensation requirements

    New Jersey generally requires employers to maintain workers’ compensation coverage or obtain approval to self-insure. The rule depends on the business structure and who performs services:

    • corporations generally need coverage when one or more people, including officers, perform services for financial consideration;
    • partnerships and LLCs generally need coverage when someone other than a partner or member performs services for financial consideration;
    • sole proprietorships generally need coverage when someone other than the principal owner performs services for financial consideration.

    Do not label a worker an independent contractor merely to avoid coverage. Worker classification depends on the real relationship and applicable law.

    General liability is not workers’ compensation

    Commercial general liability can address covered third-party bodily injury, property damage, completed operations, and other listed exposures. Workers’ compensation addresses covered employee work injuries and occupational illness. One does not replace the other.

    Likewise, a general liability policy usually does not replace commercial auto, professional liability, pollution, cyber, tools/equipment, builders risk, installation floater, inland marine, employment practices, or umbrella coverage.

    Insurance home-improvement contracts must identify

    New Jersey’s contractor application materials state that home-improvement contracts over $500 must be in writing and include specified business and project information. They also call for a copy of the contractor’s commercial general liability insurance certificate and the issuing insurance agency’s telephone number.

    Keep the certificate, policy, endorsements, and renewal evidence. A certificate summarizes coverage but does not create coverage or override the policy.

    Home-elevation contractors

    Home-elevation contractors face additional requirements. State guidance describes the $500,000 per-occurrence commercial general liability requirement plus at least $1 million per occurrence in cargo or other insurance specifically covering damage or loss resulting from home-elevation activities. Verify the current registration rules before bidding or renewing.

    Public work can require much more

    Public-work registration, prevailing-wage projects, bid documents, and agency contracts may impose higher liability, vehicle, workers’ compensation, bonding, safety, and reporting requirements. Do not use the home-improvement registration minimum as a public-project checklist. Read every solicitation and contract.

    How to compare contractor policies

    1. Describe operations accurately. List every trade, height, excavation, hot work, roofing, tree work, snow removal, design, environmental, and subcontracted exposure.
    2. Compare the same limits and forms. A cheaper quote may exclude the work you actually perform.
    3. Review exclusions. Watch for roofing, residential work, subcontractors, height, water damage, earth movement, professional services, pollution, EIFS, assault, and designated-work exclusions.
    4. Check completed operations. Claims can arise after the job ends.
    5. Understand subcontractor conditions. The policy may require written agreements, certificates, additional-insured status, or minimum limits.
    6. Review occurrence versus claims-made coverage. A claims-made form creates retroactive-date and tail-coverage issues.
    7. Compare deductibles and self-insured retentions. Include them in cash-flow planning.
    8. Verify insurer and producer licensing. Use New Jersey Department of Banking and Insurance resources and NMLS or other applicable official tools.

    Additional insured and waiver requests

    Clients and general contractors often request additional-insured status, primary and noncontributory wording, waiver of subrogation, or completed-operations coverage. These are not accomplished merely by typing a name onto a certificate. The policy endorsement and contract language control.

    Send the full written requirement to the insurance professional before signing the job contract. Ask what the endorsement covers, how long it applies, and whether an additional premium is due.

    Audit exposure estimates

    Many contractor policies are rated using estimated payroll, sales, subcontractor cost, or other exposure. At audit, the insurer can adjust the premium. Maintain payroll, sales, job, subcontractor, and certificate records; classify work accurately; and budget for audit changes.

    Do not rely on instant “AI” quote promises

    An online intake tool can collect information or route a submission, but no tool can honestly promise to shop every carrier or identify the cheapest compliant policy without complete underwriting data and policy-form review. Do not upload confidential payroll, customer, claim, or employee data without understanding who receives it and how it is used.

    Complaints and verification

    Registration questions go to the New Jersey home-improvement contractor business section. Insurance-company or producer complaints can be filed with the New Jersey Department of Banking and Insurance. Workers’ compensation requirements and employer guidance are available from the New Jersey Department of Labor.

    Bottom line

    Meet the registration minimum, but buy for the actual work and contracts. Verify workers’ compensation obligations, disclose every operation, compare exclusions and endorsements rather than price alone, and keep audit-ready records.

    Official sources

    This article provides general business and insurance information, not legal, tax, or coverage advice.

  • How to Compare Health Insurance Plans in New Jersey: Costs, Networks and Coverage

    Choosing a health plan in New Jersey requires more than finding the lowest monthly premium. A plan can look inexpensive but cost considerably more if its deductible is high, your doctors are outside its network, or your prescriptions are not covered favorably.

    This guide explains a reliable comparison process for individual and family coverage. It does not recommend a particular insurer or replace advice from a licensed broker, enrollment assister, tax professional, or healthcare provider.

    Start with New Jersey’s official marketplace

    Get Covered New Jersey’s Shop and Compare tool is the official starting point for marketplace coverage. It can compare premiums, covered doctors, estimated annual costs, and potential financial help before an application is submitted.

    Open Enrollment for 2026 has closed. People with qualifying life events may be eligible for a Special Enrollment Period. Get Covered New Jersey also provides certified enrollment assisters and brokers for applicants who need help.

    Compare these costs using the same assumptions

    • Monthly premium: what you pay to keep the policy active.
    • Deductible: what you may pay before much of the plan’s cost sharing begins.
    • Copayments and coinsurance: your share of office visits, tests, prescriptions and other services.
    • Out-of-pocket maximum: the annual limit on covered in-network cost sharing, subject to the policy’s rules.
    • Estimated annual cost: premiums plus reasonable estimates for the care and prescriptions your household expects to use.

    Compare every plan using the same expected doctor visits, medications and other care. A low-premium plan is not necessarily the lowest-cost option for someone who expects regular treatment.

    Verify networks and prescriptions directly

    Check the insurer’s current directory for every important doctor, hospital, laboratory and behavioral-health provider. Then call the provider and insurer if participation is essential. Directories can change, and a healthcare system may participate differently across plan networks.

    Review the plan’s current formulary for each prescription, including the drug’s tier, prior-authorization rules, quantity limits and preferred pharmacies. Do not assume that a medicine covered by one plan will receive the same treatment under another.

    Estimate financial assistance carefully

    The official marketplace can estimate federal premium tax credits and available New Jersey financial help using household information. Income changes can affect assistance, so update estimates honestly and follow marketplace instructions. A general chatbot should not be trusted to determine final subsidy eligibility or tax consequences.

    Use AI only for low-risk organization

    An AI tool can help turn public plan definitions into a checklist or suggest questions for a broker. It cannot verify a live provider network, guarantee coverage, calculate final eligibility, or replace the controlling plan documents.

    Do not upload insurance cards, medical records, claim histories, account numbers, Social Security numbers or unredacted benefit documents to a general-purpose chatbot. Use the official marketplace and insurer portals for sensitive information.

    Final comparison checklist

    1. Confirm marketplace eligibility and available financial help.
    2. Compare estimated total annual costs, not premiums alone.
    3. Verify important doctors, hospitals and prescriptions.
    4. Read exclusions, referral rules and prior-authorization requirements.
    5. Get certified help when the consequences of a choice are unclear.

    A careful comparison will not predict every medical expense, but it provides a far stronger basis for choosing coverage than an automated “savings” promise.